Categories
Buyer's Guide, Seller's Guide, Market Trends & InsightsPublished September 14, 2026
What Does "Contingent" Really Mean in a Home Offer?
What Does "Contingent" Really Mean in a Home Offer?
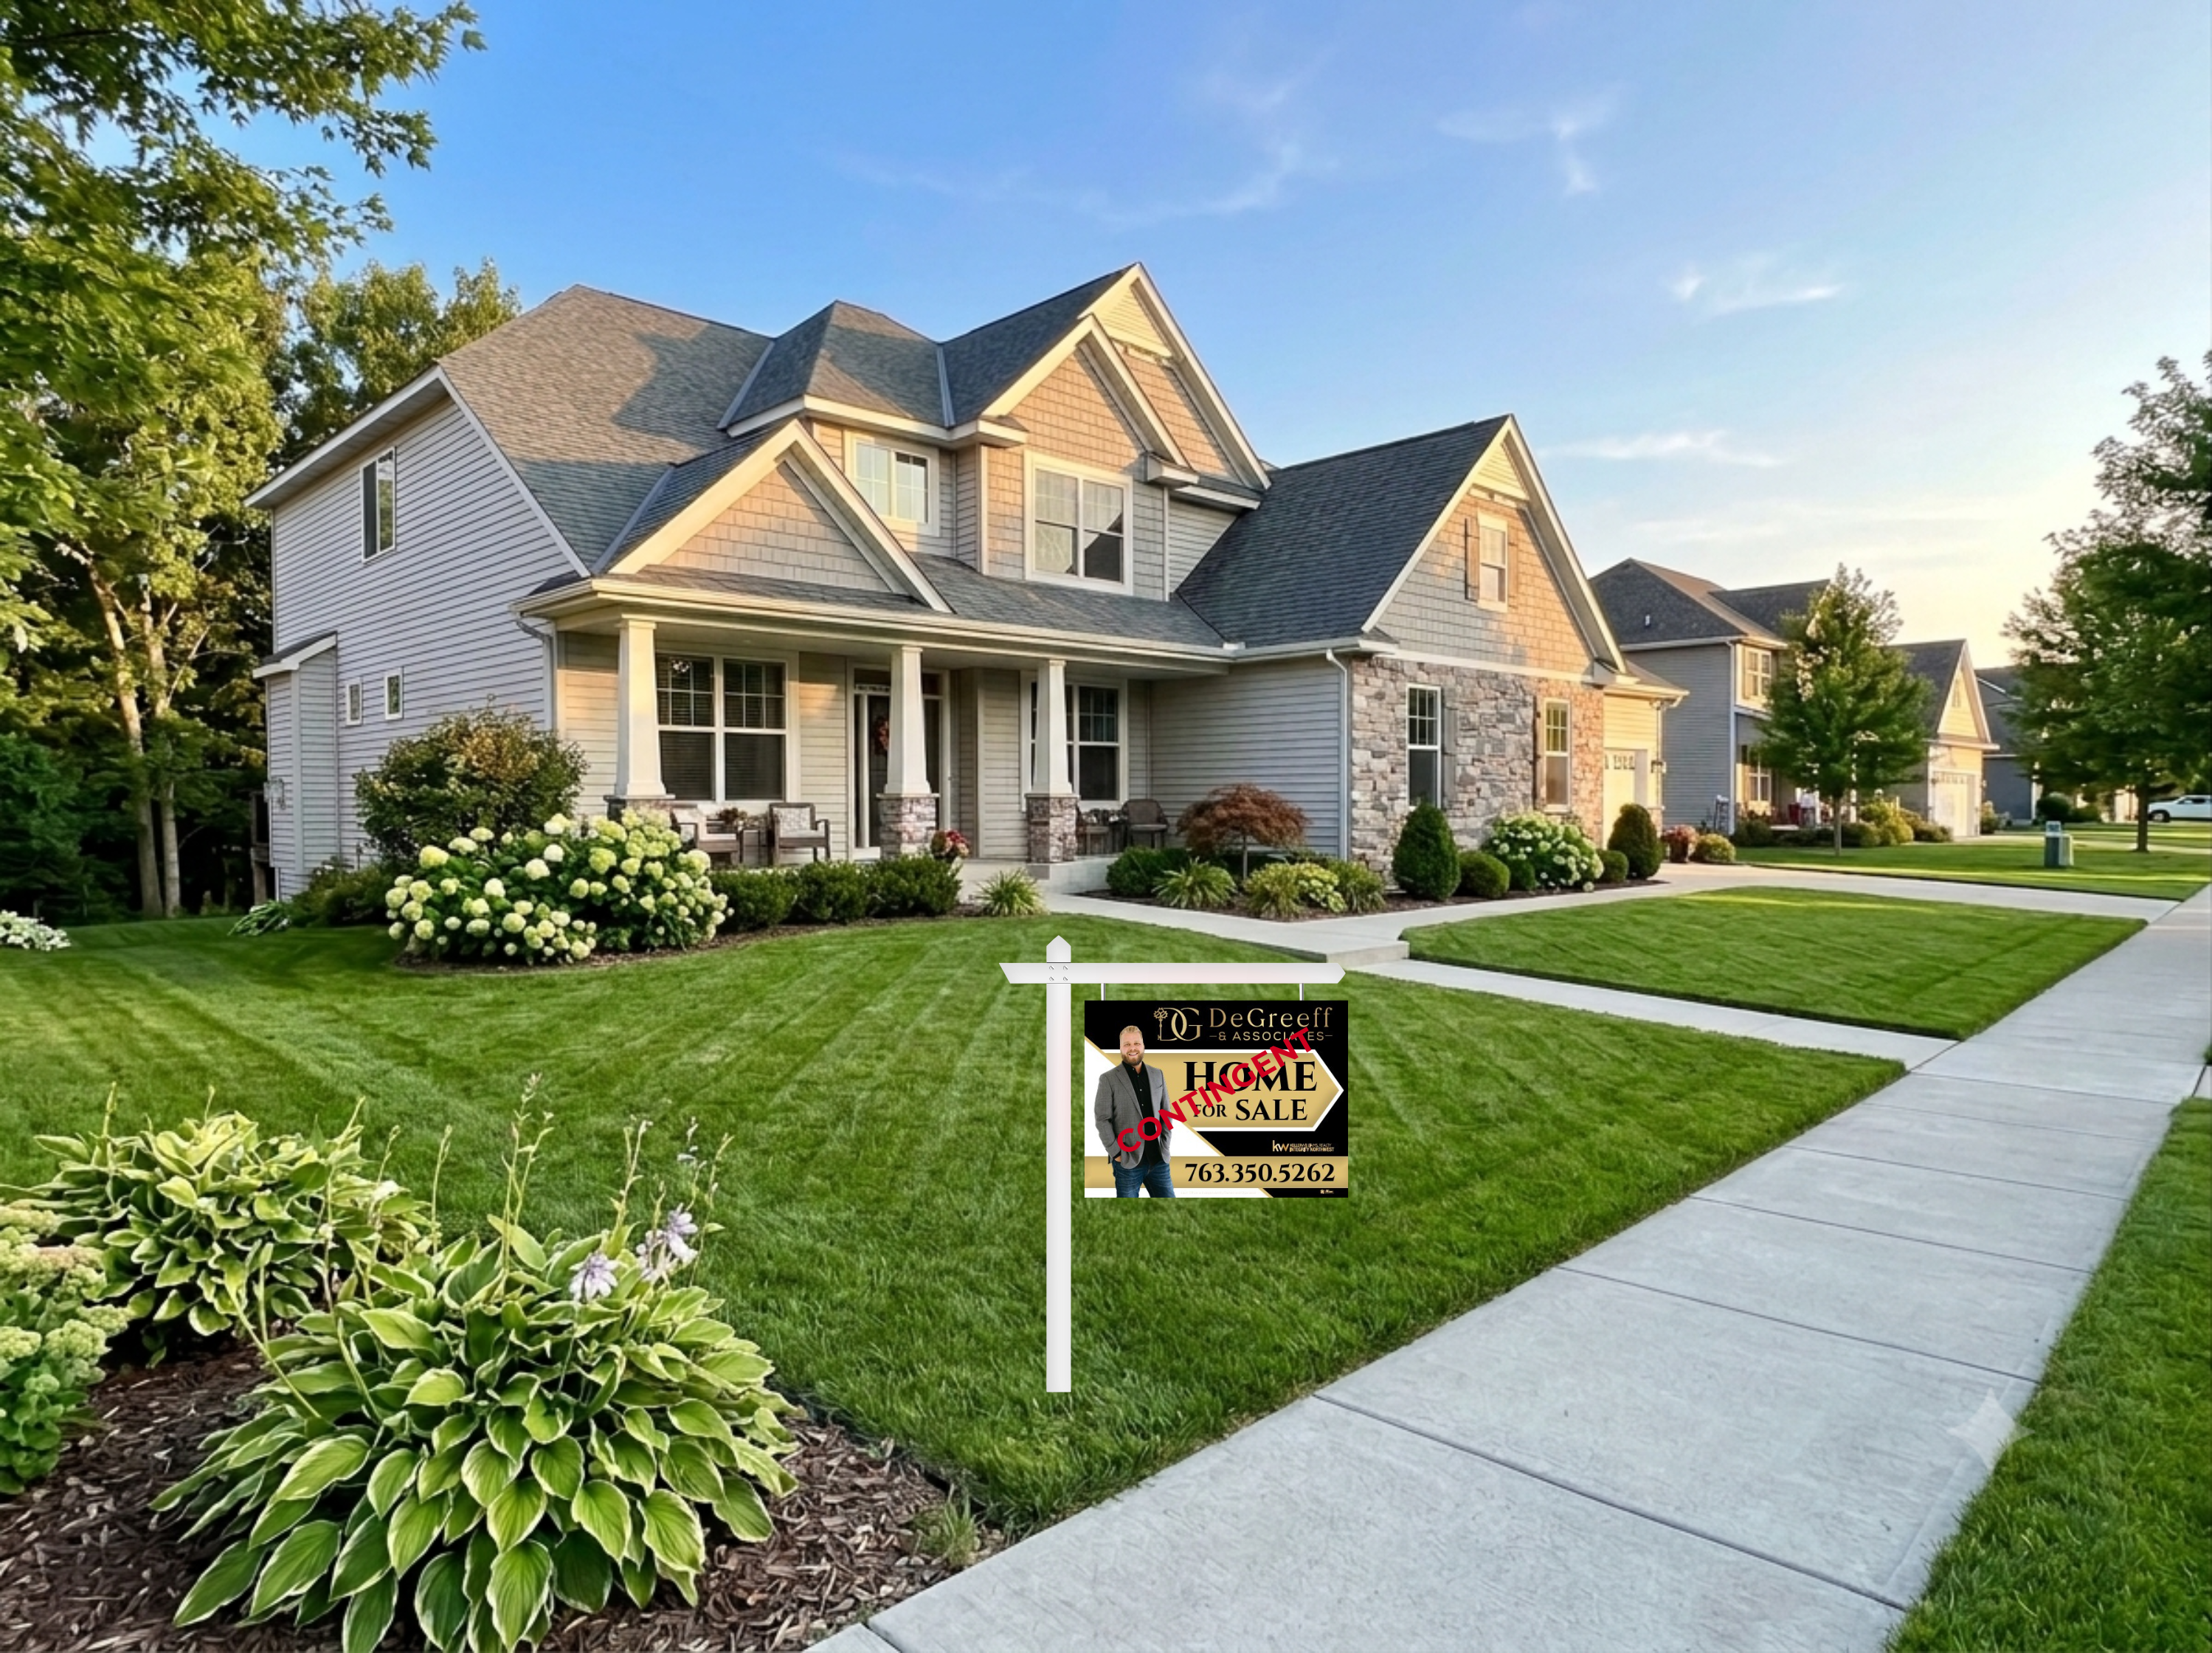
If you've been scrolling listings in Anoka, Sherburne, or Wright County and noticed a home marked "contingent," you've probably wondered what that actually means for you. Is it still available? Should you make a backup offer? Should you even bother? Understanding what does contingent mean in a home offer can save buyers and sellers a lot of confusion, and it's one of the most common questions we field from clients across the north metro.
In simple terms, a contingent offer means a buyer and seller have agreed on a price, but the sale isn't final yet. It's still hanging on one or more conditions being met before closing day arrives.
Contingent vs. Pending: What's the Difference?
Buyers browsing the MLS often confuse "contingent" with "pending," but they mean different things.
- Contingent means an offer has been accepted, but specific conditions still need to be satisfied. There's a real chance the deal could fall through.
- Pending means those conditions have been met (or waived), and the sale is moving toward closing with little left to resolve.
A home in a small town like Zimmerman or Big Lake might sit contingent for a few weeks while the buyer's inspection, appraisal, and financing all clear. Once those boxes are checked, the listing typically moves to pending, and closing is usually just around the corner.
The Most Common Types of Contingencies
Not all contingencies are the same, and the ones written into an offer make a real difference in how secure that deal actually is.
Inspection contingency. This gives the buyer a window, often 7 to 10 days, to have the home professionally inspected. If the inspector turns up a cracked foundation, an aging furnace, or a roof nearing the end of its life, the buyer can negotiate repairs, request a credit, or walk away with their earnest money intact.
Financing (or mortgage) contingency. This ties the sale to the buyer actually getting approved for their loan. If a job change or credit issue derails financing, this contingency lets the buyer exit without losing their deposit.
Appraisal contingency. Lenders won't loan more than a home is worth, so this contingency protects the buyer if the appraised value comes in below the purchase price. Without it, a buyer could be stuck covering the gap in cash.
Home sale contingency. Less common in a competitive market, this makes the purchase dependent on the buyer selling their current home first. Sellers tend to be wary of these, since they add uncertainty and stretch out the timeline.
Why This Matters for Sellers Along Highway 10 and Beyond
If you're selling a home anywhere from Elk River to Ramsey, understanding contingencies helps you evaluate offers with clear eyes, not just the highest number on the page. Two buyers might offer the same price, but if one has a rock-solid pre-approval and a shorter inspection window, that offer often carries less risk of falling apart three weeks from now.
Some sellers choose to keep accepting "backup offers" while their home is contingent, especially in a season with steady buyer traffic. That way, if the first deal collapses over an inspection dispute or a financing hiccup, there's already a second buyer lined up and ready to go.
Why This Matters for Buyers
For buyers, contingencies aren't red tape. They're protection. They're what stand between you and losing your earnest money if the inspection reveals a hidden problem or your loan falls through unexpectedly.
That said, in a competitive north metro market, some buyers choose to waive certain contingencies to make their offer more appealing to a seller with multiple bids on the table. That can work in your favor, but it also raises your risk. Waiving an inspection contingency, for example, means you're agreeing to buy the home as-is, sight-unseen issues and all.
This is exactly where having an experienced local agent matters. The right guidance helps you decide which contingencies are worth keeping and which ones you can comfortably let go of, based on the specific home, the specific seller, and how competitive that particular listing really is.
A Quick Example From the North Metro
Say a buyer puts in an offer on a three-bedroom rambler in Otsego, and the seller accepts. That listing now shows as contingent, not because anything is wrong, but because the buyer still has a 10-day inspection window and their lender needs another two weeks to finalize underwriting.
During that stretch, the inspector finds a minor issue with the sump pump. The buyer and seller negotiate a small credit, everyone signs off, and the loan clears underwriting a week later. Only then does the listing flip to pending, and the closing date gets locked in. That's the contingent period in action: not a red flag, just the normal working-out of the details before a sale becomes official.
Making Sense of Your Own Offer
Every contingency in a purchase agreement exists to answer one question: what happens if something doesn't go as planned? A well-written offer anticipates the "what ifs" so you're not caught off guard partway through the process.
Whether you're writing an offer for the first time or trying to figure out why a home you liked suddenly shows as contingent instead of active, it helps to have someone walk you through exactly what those terms mean for your specific situation.
If you're getting ready to make an offer on a home in the north metro, our team can help you build a strategy that protects you without pricing you out of a competitive deal. Reach out today to talk through your offer strategy, and we'll help you understand exactly what you're agreeing to before you sign anything.
Steven DeGreeff
Owner / Realtor® | Degreeff and Associates | Steven DeGreeff | Keller Williams Realty Integrity NW
or another way